After a collision in a parking lot or a windshield cracked by a stone, the repair bill arrives. Your insurance covers part of it, but a portion remains your responsibility: this is the deductible. At Macif, this remaining charge varies depending on the coverage concerned, the chosen plan, and sometimes even the driver behind the wheel at the time of the incident. Understanding these mechanisms helps avoid unpleasant surprises during compensation.
Contractual deductible and legal deductible: two distinct logics
Before looking at the amounts, it is essential to distinguish between two types of deductibles that can coexist in the same auto insurance contract.
The contractual deductible is freely set by the insurer in the specific conditions. This is the one you negotiate at the time of subscription. It applies to most coverages (all accident damage, theft, glass breakage).
The legal deductible, on the other hand, is imposed by regulations. It comes into play in specific cases, such as natural disasters. Its amount is regulated by insurance law, and neither you nor Macif can modify it.
Why does this distinction matter? Because in the event of a natural disaster, you cannot buy back or eliminate the legal deductible, even if your contract provides for a buyback option for the contractual deductible. These are two separate mechanisms. Many insured individuals discover this nuance at the time of the incident, when it is too late to act.
To consult in detail the amount of the Macif auto deductible according to each coverage, you must refer to the specific conditions of your own contract, as the amounts vary from one insured person to another.
Macif glass breakage deductible: repair or replacement, the difference in treatment
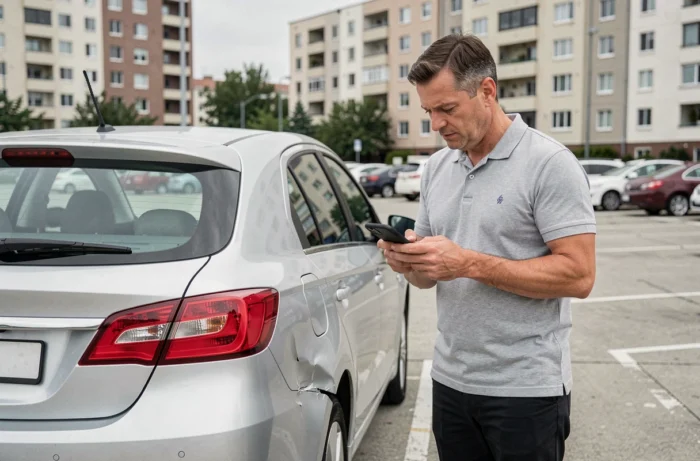
Glass breakage is the most common claim in auto insurance. At Macif, as with most insurers, coverage depends on the nature of the intervention.
When a chip on the windshield can be simply repaired (resin injection), the repair is often covered without a deductible. The cost is low for the insurer, and the operation preserves the original glass.
In contrast, if the windshield needs to be completely replaced, a deductible or specific remaining charge applies. The difference in treatment can represent several hundred euros depending on the vehicle. The moral: getting a chip repaired quickly, before it spreads, avoids both a costly replacement and a higher deductible.
Loan of vehicle and occasional driver: a often overlooked increased deductible
You lend your car to a friend or family member for a weekend. An accident occurs. Who pays the deductible?
At Macif, the deductible may be increased if the driver behind the wheel is not the usual driver designated in the contract. This increase is stipulated in the contract clauses, but it often goes unnoticed at the time of subscription.
In practice, two situations arise:
- The occasional driver is declared in the contract: the standard deductible applies, without any surcharge at the time of the incident.
- The occasional driver is not declared: the deductible may be increased, or even the compensation reduced according to the terms of the contract.
- The vehicle is lent to a young, undeclared driver: the increase can be even more significant due to the risk profile.
Before handing over your keys, check the vehicle loan conditions in your specific conditions. Adding a secondary driver to the contract often costs less than paying an increased deductible after an incident.
Macif deductible buyback: eliminating the remaining charge on certain claims
Macif offers a deductible buyback option on its auto contracts. The principle is simple: for an additional premium, you reduce or eliminate the deductible on certain coverages.
Why consider this option? If you use your vehicle daily in an urban area, the likelihood of minor claims (collisions, glass breakage, parking damage) increases. Without a deductible buyback, each small claim generates a remaining charge that, accumulated over a year, can far exceed the cost of the option.
Conversely, if you drive little or your vehicle is parked in a closed garage, the deductible buyback represents an additional cost that is not always justified. The calculation depends on your actual usage.
What the deductible buyback does not cover
Be careful: the deductible buyback does not eliminate the legal deductible (natural disasters, for example). It only applies to the contractual deductible defined in your specific conditions. If your vehicle is damaged during a flood classified as a natural disaster, the legal remaining charge will apply despite the buyback.
Reading your specific conditions: the only reliable document
The deductible amounts communicated on comparison sites or forums do not reflect your personal situation. At Macif, the exact amount depends on several parameters:
- The chosen plan (Economical, Expanded, Protective, or Comfort), each level offering different deductibles.
- The type of coverage concerned: theft, glass breakage, all accident damage, fire.
- The options subscribed, notably the deductible buyback.
- The profile of the main driver and declared drivers.
Only your specific conditions indicate the exact amount of your deductible for each coverage. This document, provided at subscription and available in your personal Macif space, details item by item what remains your responsibility in the event of a claim.
An auto contract is not just about the amount of the annual premium. The deductible determines what you will actually pay when a claim occurs. Comparing two quotes without looking at the deductibles is like comparing two prices without reading the labels.